personal finance

A person comparing savings account details on a laptop, checking an 8% savings rate and account rules
Expenses

Why an 8% Savings Rate Isn’t the Whole Story

Three well-known UK banking brands are now dangling the same headline number in front of savers: 8%. It sounds like a rare win in an otherwise cautious savings market. But an interest rate on its own is just one line of a much longer contract, and the fine print is where a “great” account can quietly turn into a mediocre one for your particular situation. If you’re trying to decide whether to open one of these accounts — or any high-rate saver — the real question isn’t “is 8% good?” It’s “does this account’s rules match how I actually save?”
A person reviewing a monthly expense tracker on a laptop, illustrating a simple expense tracking method for better money clarity
Expenses

Where Your Money Actually Goes: A Simple, Judgment-Free Way to Start Tracking Expenses

You probably know roughly what you earn. Do you know what you actually spend? Most people don’t — not because they’re careless, but because modern spending is designed to be invisible. A card tap, an autopay, a subscription that renews itself quietly every month: none of it demands your attention the way handing over cash once did. That’s exactly why a simple, one-month tracking habit can feel almost startling the first time you try it. Not because you’re bad with money, but because nobody’s finances are visible by default anymore.

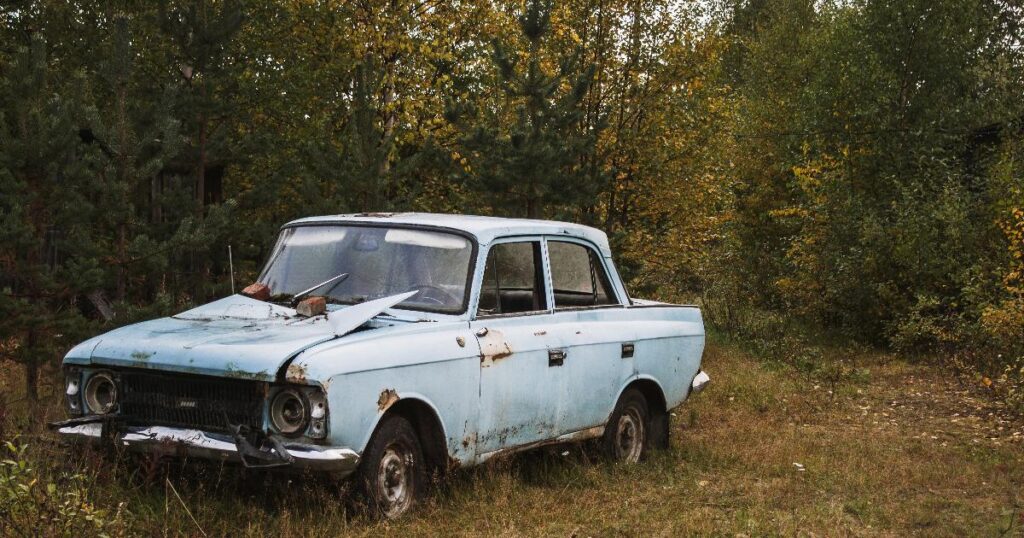
A rusty first car parked in a driveway, showing how total cost of ownership can matter more than the sticker price
Terms

What a Rusty First Car Can Teach You About Money That a New One Never Will

Somewhere in your family’s history, there’s probably a car with a story: a hand-me-down with a failing air conditioner, a stick shift nobody quite trusted, or a floor patched with plywood because replacing it seemed like more trouble than it was worth. These cars weren’t glamorous. But they may have taught their drivers more about money than any finance class ever could.

A person reviewing monthly expenses on a calculator, illustrating the rule of 25 retirement number
Budgeting

The Rule of 25: A Simple Way to Turn Spending Habits Into a Retirement Number

Retirement can feel like a fog — a vague sense that you should be “saving more,” with no clear sense of how much is actually enough. The Rule of 25 cuts through that fog with one multiplication: take what you spend in a year and multiply it by 25. Suddenly retirement stops being a mood and becomes a number you can write on a sticky note. But the most useful part of this rule isn’t the number itself — it’s what it reveals about your spending, and how much power you already have to change your own target.

A calm budgeting conversation about whether to lend money, gift it, or say no
Expenses

Should You Lend It, Gift It, or Say No? A Calmer Way to Decide

A cousin needs help with rent. A close friend wants to borrow for a car repair. A sibling asks for a “quick loan” until payday. In the moment, saying yes feels like the kind thing to do — and saying no feels almost impossible. But money moving between people who love each other is never just a transaction. It quietly rewrites the rules of the relationship, whether or not either side notices at the time.

Scroll to Top