personal finance

A small emergency fund in a savings jar beside bills and a calculator, showing how an emergency fund helps cover surprise expenses.
Emergency Fund

The Emergency Fund: Why Even High Earners Need One Before the Next Surprise Bill

A good salary can feel like proof that your finances are solid — until a cracked tooth, a layoff notice, or a leaking roof shows up on the same week rent is due. Suddenly the question isn’t how much you earn, it’s how much you have sitting somewhere, ready, that isn’t already spoken for. That gap between income and available cash is exactly where an emergency fund does its quiet, unglamorous work.
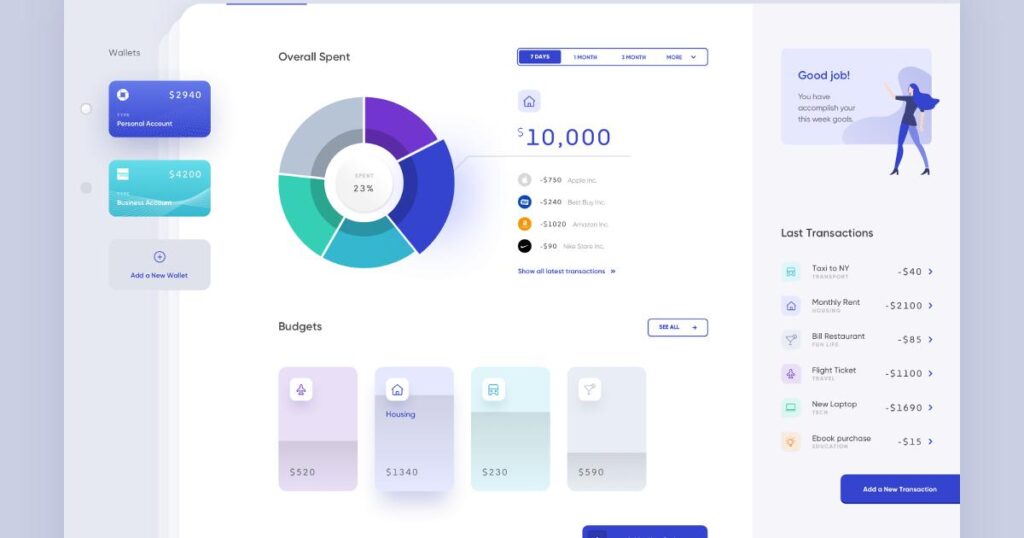
A person comparing budgeting app dashboards on a laptop, highlighting the best money app for habits and planning
Money Habits

Empower or Monarch: Which Money App Actually Fits Your Habits?

If you’ve ever opened a budgeting app once, felt a flicker of motivation, and then never logged in again, you already know the real problem isn’t the software — it’s whether the tool matches how you actually behave with money. That’s the question worth asking before comparing Empower and Monarch Money feature by feature: not “which app is better,” but “which app fits the habit I’m actually trying to build?”

A small stack of coins beside a savings jar, showing a simple emergency fund and the focus keyword save before you invest
Savings

Build Your Cushion First: A Calm Plan for Saving Before You Invest

If money is tight, the idea of “getting started with investing” can feel like a joke someone else gets to make. But the more useful starting point isn’t a stock market decision at all — it’s a much smaller, much calmer one: can you move a little money, on the same day every month, into an account you don’t touch? That single habit, repeated, is what turns “I never have anything left over” into “I have a cushion now.” Everything else, including investing, can wait until that cushion exists.

Person reviewing monthly bills and subscriptions to identify forgotten recurring expenses they can cut from their budget
Expenses

The $2,160 You Forgot You Were Paying

Somewhere in a climate-controlled building a few miles from your home, there might be a 10×10 unit holding a couch you don’t remember buying, boxes you haven’t opened since your last move, and a monthly charge of around $180 that hits your card without a second thought. Multiply that by twelve months and you’re looking at over $2,000 a year — money quietly leaving your account for a service that, if you’re honest, stopped delivering value a long time ago.

A simple budget notebook beside a quality pair of shoes and a coffee mug, illustrating the Buffett rule for spending
Expenses

The Buffett Rule for Spending: Buy Less, But Never Cheap Out on What Matters

Warren Buffett has a net worth of over $150 billion and still lives in the same five-bedroom house he bought in Omaha in 1958. That contrast — vast wealth, modest daily life — is the part of his story that gets repeated the most. But it’s not really the interesting part. The interesting part is what he does spend on, and why. Buffett isn’t frugal for its own sake. He’s selective. And that selectiveness, more than the net worth, is something an ordinary household budget can actually learn from.

Scroll to Top